Merchant Cash Advance Cost Disclosure: Why Your State, Not Washington, Decides What You See
The CFPB's small-business lending data rule leaves out merchant cash advances. Here's what that means for the cost disclosures you get.
Guide · · 6 min read
If you’ve ever looked at a merchant cash advance offer and tried to compare it with a bank loan, you probably noticed that the numbers don’t line up neatly. A recent federal decision helps explain why that keeps happening. It also shows where to look for clearer information.
In its annual Fair Lending Report, the Consumer Financial Protection Bureau (CFPB) restated that merchant cash advances (MCAs) are left out of its Section 1071 small-business lending data rule, according to a report by deBanked. Below is what that means in plain terms, and how it affects your borrowing readiness and the cost information you’re likely to see.
The short version
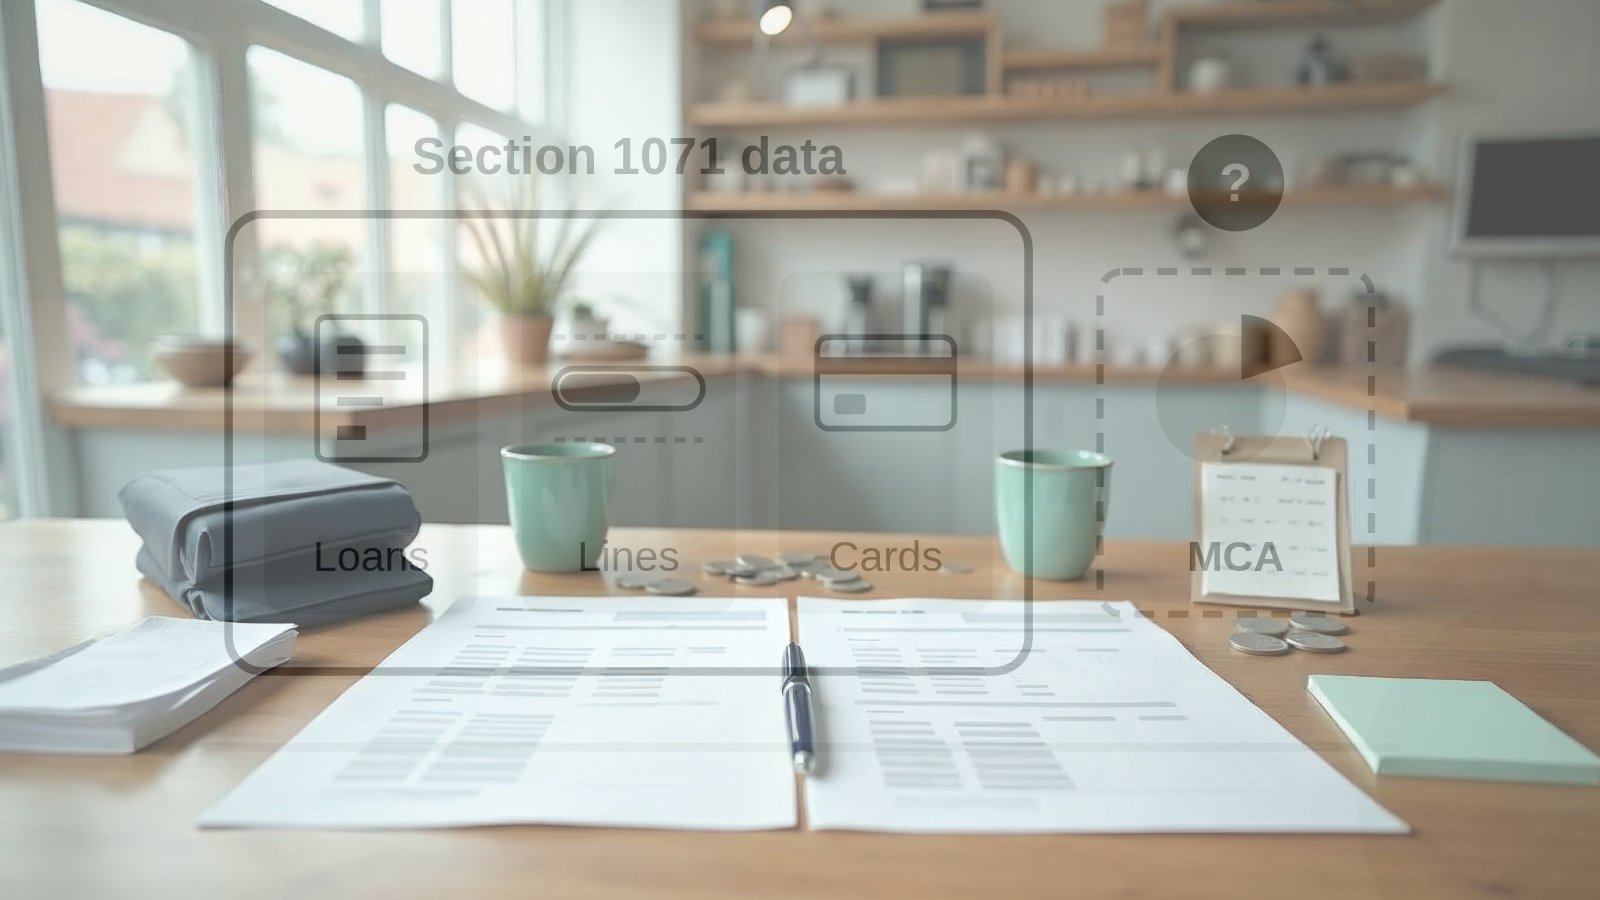
- A federal rule known as Section 1071 covers data on small-business loans, lines of credit and credit cards. It does not cover merchant cash advances.
- There is no federal rule that sets how MCA costs must be disclosed to you.
- Any standardized cost disclosure you receive for an MCA comes from state law, and those laws vary.
What is Section 1071, anyway?
Section 1071 is a federal requirement for lenders to collect and report data about small-business credit applications. The goal is to shed light on fair lending in the small-business market. The CFPB’s final rule, titled “Small Business Lending Under the Equal Credit Opportunity Act (Regulation B),” was published in the Federal Register on May 1, 2026. It took effect June 30, 2026, and lenders must comply starting January 1, 2028.
The rule narrows what counts as a “covered credit transaction.” deBanked’s account of the Fair Lending Report says this focuses the rule on the core products small businesses use most: loans, lines of credit and credit cards. As the report puts it, quoted by deBanked: “the rule sets forth certain exclusions: merchant cash advances, agricultural lending, and small-dollar business credit.”
The rule’s own summary in the Federal Register confirms that it “excludes merchant cash advances (MCAs), agricultural lending, and small dollar loans.” A secondary legal summary from Credible Law notes that the small-dollar cutoff is $1,000.
The rule also applies only to institutions above a 1,000-origination threshold. The CFPB estimates that this still covers roughly 92 to 93 percent of small-business loan originations by depository institutions, compared with 94 to 95 percent if the threshold were 100.
How is an MCA different from a loan?
This matters for understanding why the products get treated differently. According to Credible Law’s summary, the rule describes an MCA as an agreement where a business gets a lump-sum payment in exchange for the right to a percentage of its future sales or income, up to a ceiling amount.
In practice, an MCA is structured as a purchase of your future receivables rather than as a loan. You’ll see different vocabulary:
- Advance: the lump sum you receive.
- Purchase price: what the provider pays for your future receivables (the advance).
- Factor rate: the multiplier used to set the total amount you’ll remit.
- Holdback: the percentage of your sales the provider collects.
- Remittance: the payments that flow back to the provider, often daily or weekly.
Does this exclusion settle whether an MCA is “credit”?
No, and it’s worth being clear about this. Credible Law reports that trade associations representing MCA providers asked the CFPB to declare that MCAs are categorically not “credit” under the Equal Credit Opportunity Act. The Bureau left MCAs out of the reporting rule but did not make that declaration.
The Federal Register text also says the Bureau “may revisit the scope of its coverage of credit products in future rulemakings” and “will continue to monitor developments in the markets for MCAs.” The current exclusion is a scoping decision for a data rule. It is not a final word on what an MCA legally is, and it could change.
The exclusion also doesn’t make an MCA easier or harder to qualify for. It concerns what data lenders report, not who gets approved.
So who decides what cost disclosure you get?
Your state does. There is no federal cost-disclosure rule for MCAs, so your disclosure protections depend on state law, according to a 2026 state-by-state overview from RAN Funding, a commercial MCA provider. That page says California requires the cost to be expressed as an APR.
More broadly, a growing number of states now require providers of commercial financing to give cost disclosures, which can include an estimated APR. In some states the rules reach brokers too. These laws are changing, so check your own state’s current rules rather than relying on any list you find online, including this one.
If you’re in a state with a disclosure law, you can usually expect a standardized summary of the deal’s cost. If you’re not, you may only see the factor rate and payment terms, and you’ll need to do more of the comparison work yourself.
Why this matters for your credit and borrowing readiness
At Credisian we look at everything through the lens of your business credit. Here’s how this connects.
1. You’re the one comparing apples and oranges. A factor rate isn’t an annual rate. It doesn’t account for how fast you remit the money. Two offers with the same factor rate can cost very differently on an annualized basis depending on the remittance schedule. Where your state requires an estimated APR, that figure comes from the provider’s disclosure and is your best tool for a like-for-like comparison with a term loan or line of credit.
2. Your cash flow is part of your creditworthiness. Daily or weekly remittances pull directly from revenue. Before you sign, map out how the holdback affects your ability to pay suppliers, cover payroll and stay current on any existing loans or cards. Missed payments elsewhere can hurt the business credit profile you’ve worked to build.
3. Ask how the arrangement shows up. Ask any provider directly whether and how they report the arrangement, and whether a business credit check is part of their process. Get the answers in writing. Knowing this helps you plan your next financing step.
4. An MCA isn’t right for every business. Whether one makes sense depends on your sales pattern, margins, timeline and other options. If you qualify for a loan or line of credit, it’s worth seeing those offers side by side before deciding.
Your comparison checklist
Before accepting an MCA, gather these items and set them next to any loan offers:
- The state-required disclosure, if your state has one. Ask for it if you don’t see it.
- Purchase price: the actual advance amount you’ll receive.
- Factor rate: and the total amount you’ll remit as a result.
- Holdback percentage: how much of each day’s or week’s sales goes to the provider.
- Remittance schedule: daily, weekly, fixed or variable.
- Estimated APR, if the provider discloses one under state law.
- For each loan offer: the stated rate, APR, fees, term and payment schedule as the lender gives them.
If a provider can’t or won’t explain any of these in plain language, treat that as useful information in itself.
What to watch next
- The 2028 compliance date. Loan, line and card data collection under Section 1071 starts January 1, 2028. MCAs stay outside it unless the rule changes.
- Future CFPB action. The Bureau has said it may revisit product coverage and is watching the MCA market.
- Your state legislature. New disclosure and registration requirements keep emerging. A quick check of your state’s financial regulator website before you shop can save you surprises.
Key takeaways
The federal small-business lending data rule doesn’t cover merchant cash advances, and no federal rule sets how their costs are disclosed. Your state’s law is what decides whether you see a standardized cost figure such as an estimated APR. Whatever state you’re in, gather the full set of terms, compare them carefully against loan offers, and think through how the remittances will affect your cash flow and your business credit.
Sources
- deBanked, “CFPB Reaffirms Excluding Merchant Cash Advances From Section 1071,” published 2026-10-13: https://debanked.com/2026/10/cfpb-reaffirms-excluding-merchant-cash-advances-from-section-1071/
- Federal Register, “Small Business Lending Under the Equal Credit Opportunity Act (Regulation B),” 91 FR 23530, published 2026-05-01: https://www.federalregister.gov/documents/2026/05/01/2026-08494/small-business-lending-under-the-equal-credit-opportunity-act-regulation-b
- Credible Law, “CFPB’s New 1071 Rule Excludes Merchant Cash Advances,” page date unconfirmed (around early September 2026): https://crediblelaw.com/cfpb-1071-rule-merchant-cash-advance-exclusion/
- RAN Funding, “Merchant Cash Advance Disclosure Laws by State (2026),” published about 2026-10-07 (commercial source): https://ranfunding.com/merchant-cash-advance-disclosure-laws-by-state/
About the author
The Credisian Editorial Team writes plain-English guides and news on business credit and borrowing, sourced and checked under our editorial policy, to help owners make informed funding decisions.

