Business Loan Denied: How to Find the Reason and Plan Your Next Move
A business loan denied by a bank or lender is information, not a verdict. Learn how to get the reasons, sort what you can fix and decide whether to reapply.
Guide · · Updated Oct 29, 2026 · 6 min read

Business loan denied? It can feel like the end of the road, but it is better treated as the start of a short investigation into why it happened.
This guide follows three steps in order: diagnose, correct, then consider reapplying. It separates what federal rules say from what we suggest. The rules are described as written, not as rights every applicant has, and our suggestions are marked as suggestions. None of this is legal advice.
Step 1: Diagnose what you were told, and when
When a bank denied your business loan, first pin down how you were told and whether the lender gave reasons. Under Regulation B (12 CFR 1002.9), which carries out the Equal Credit Opportunity Act, what you must be told depends on the business and the lender.
Revenue and credit type decide which notice rule applies.
- Gross revenue of $1 million or less in the preceding fiscal year. The lender follows the general rules, with some changes. It may tell you the decision orally or in writing. It may disclose your right to a statement of reasons when you apply instead of when it denies you. For an application made entirely by telephone, an oral statement of the decision and of your right to reasons is enough. Where a written notice is given, it states either the specific reasons or your right to a statement of reasons. If you request that statement within 60 days of the lender’s notification, the lender supplies it within 30 days of your request.
- Gross revenue above $1 million in the preceding fiscal year. The lender must tell you its decision within a reasonable time, orally or in writing. It must send a written statement of reasons only if you make a written request within 60 days of its notification. Notice within 30 days of a completed application counts as reasonable, but that is a safe harbor, not a promise of a 30-day written notice.
- Trade credit, credit incident to factoring, and similar business credit. These follow the larger-business rule whatever your revenue. Trade credit generally means a buyer-seller arrangement, such as a supplier financing equipment or inventory, not financing from a bank. Factoring itself is a purchase of receivables and is outside the rule, but credit extended as part of a factoring arrangement is covered.
A few details can change the picture:
- A lender may rely on your statement about your revenue size. Applications to start a business follow the smaller-business rule, and a sole proprietor’s revenue is the proprietorship’s revenue.
- A lender may choose to give every business applicant the fuller notice, whatever its size.
- A lender that received no more than 150 applications in the preceding calendar year may satisfy the section, including reasons, with oral notifications.
- If your application was missing information you could supply, the lender may deny it for being incomplete or send a written notice saying what is needed, how long you have and that missing it ends consideration. If it had enough data to decide, it cannot cite incompleteness as the reason.
- If one application went to several lenders through a third party and you accept or use the credit one lender offers, the other lenders need not notify you. If no credit is offered, or you accept or use none, each lender that denies you must notify you directly or through the third party. A combined notice must name each lender and either describe your right to reasons or label each lender’s reasons.
- If you expressly withdraw an application, the lender does not have to follow these notice rules.
What counts as a specific reason. Where reasons are given, they must be specific and state the principal reasons. “Internal standards or policies” or “failed to achieve a qualifying score” is not enough by itself. The notice need not explain how a factor hurt you, and a statement that a credit report was used does not meet the requirement either. The Fair Credit Reporting Act separately requires some disclosures, which this guide does not cover.
The 60-day clock. Notification happens when the lender mails or delivers the notice to your last known address or, for an oral notice, tells you the decision. The 60 days run from then.
Our suggested actions for this step:
- Find the notice, or write down when and how you were told, and whether it gave reasons or a way to ask for them.
- If you have no specific reasons, ask for them. A written request is the one the rules tie to a written reply for larger businesses, so keep a dated copy of your request. Writing it is our suggestion, not a mandate.
- Ask questions. Was my application treated as complete, and if not, what was missing? Is any reason one I can correct, and with which document? Would a different amount, use of funds or product fit better? Can I reapply with you, and is there a timing policy? If a third party sent the application, which lender decided?
Step 2: Correct what the reasons point to
Sort each reason you have into a bucket. Do not guess at reasons you were not given.
- File problems. Incomplete or inconsistent documents, or an item the lender asked for and did not receive.
- Fit problems. The loan type, the use of the money, the size of the request or eligibility for the program.
- Credit and repayment problems. These concern creditworthiness and the ability to repay, which SBA lists among its 7(a) conditions. They may call for a different product, a different lender or more time.
These buckets are illustrations. No source we used says which reasons are most common.
Suggested corrections:
- Supply what was missing, and make your documents agree with each other and with the application.
- Confirm what the lender needs for a new submission. SBA’s 7(a) page says application contents vary with loan size and the lender’s processing method, and that your lender will tell you which documents are needed.
- Check the request against the program. An SBA microloan, for example, cannot pay existing debts or buy real estate, while 7(a) lists refinancing current business debt as one of its uses.
Repairing a file does not guarantee a different result, and a fit or repayment reason may not be fixable by paperwork.
Step 3: Decide whether to reapply or change course
You have three separate choices, and each needs its own decision.
- Reapply with the same lender. Ask whether it has a timing policy. We found no source that sets a waiting period, so do not assume one.
- Apply with a different lender. For SBA programs, you apply through a lender, not SBA. SBA offers its Lender Match tool for finding a participating 7(a) lender, plus District Offices and Resource Partners for help. For microloans, you work with an SBA-approved intermediary, which makes all credit decisions.
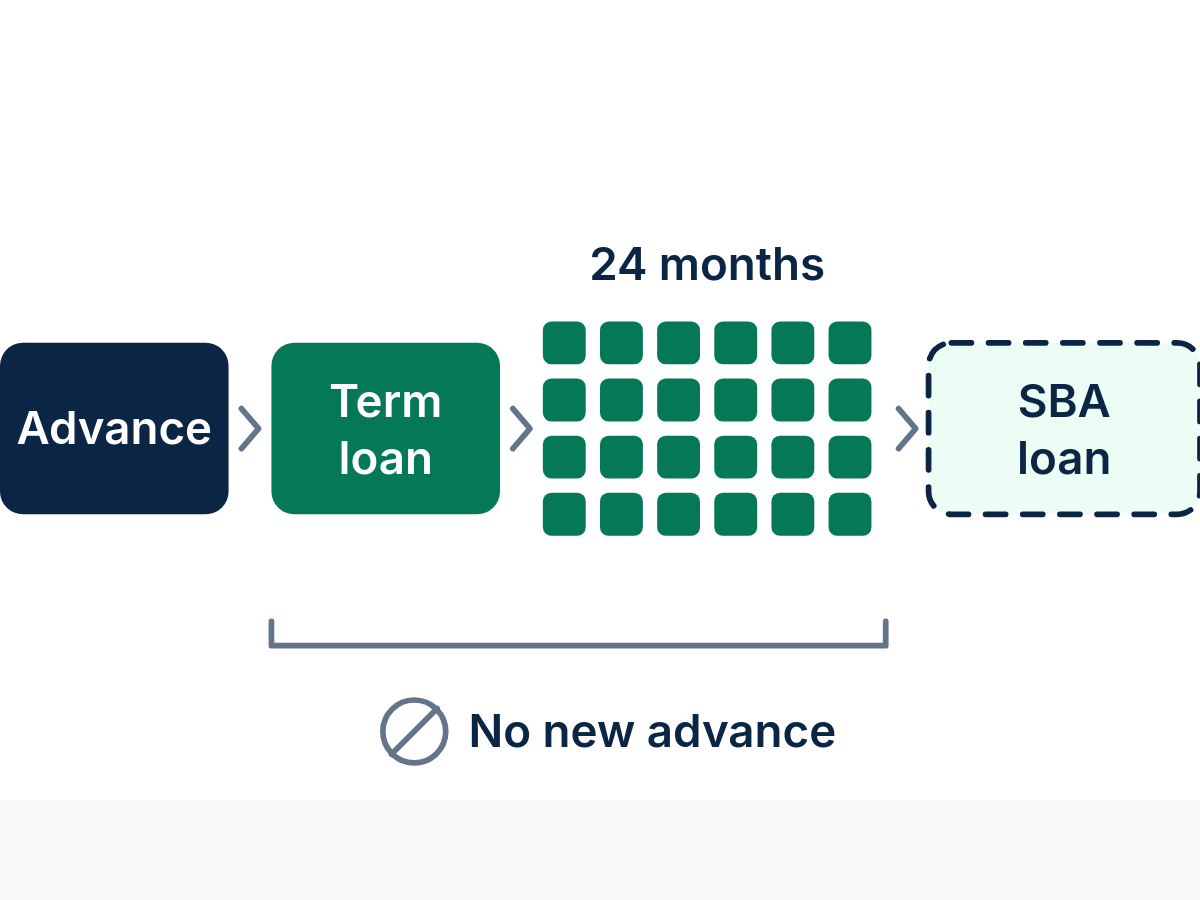
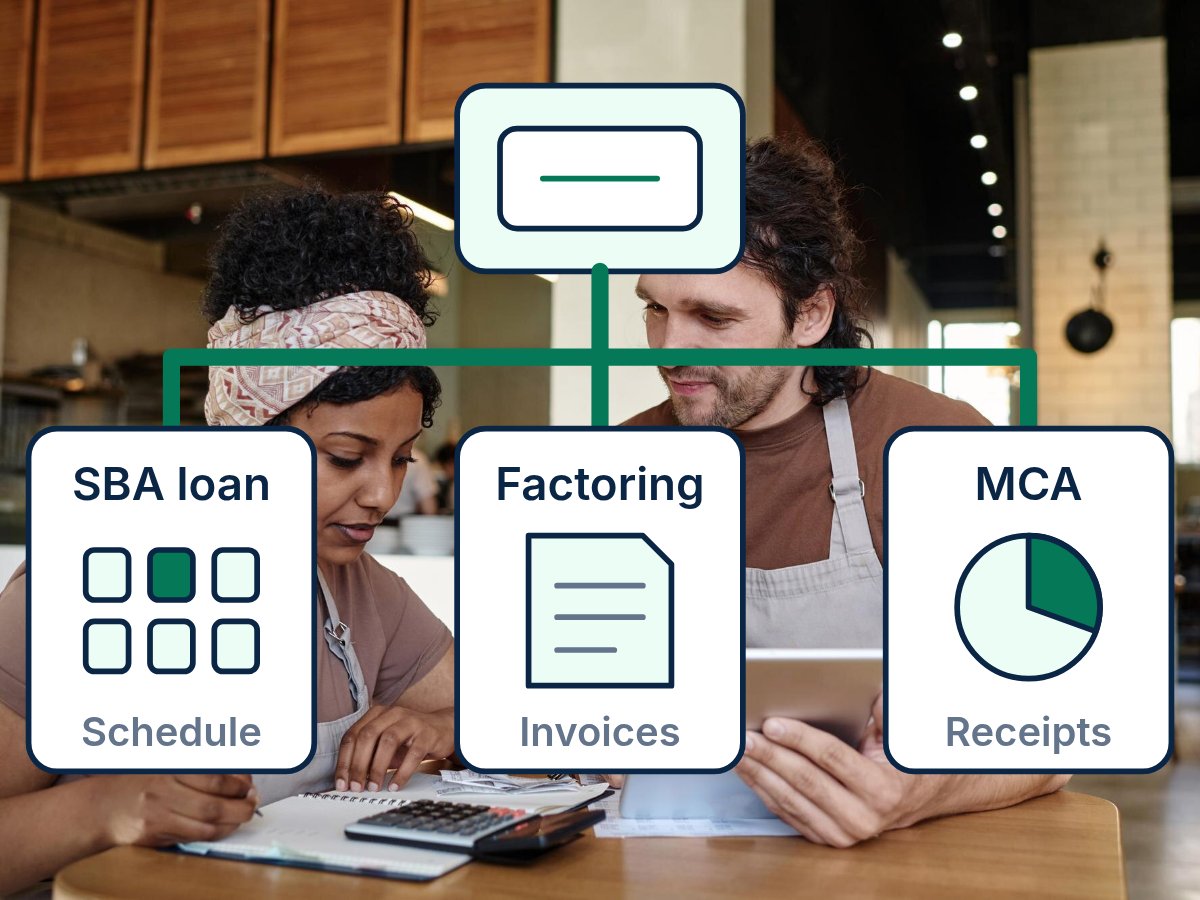
- Look at a different product. If the reasons were about fit, another product may suit better. Our alternative funding guide compares SBA loans, factoring and merchant cash advances, and our guide to reading a merchant cash advance contract covers what to ask before signing one. If existing debt is part of the picture, see the SBA refinance guide for an MCA. To browse by product, start with SBA funding options.
Reapplying is not right for every business, and no one product suits every situation. A denial is also not a route into SBA eligibility. SBA’s 7(a) page lists its conditions, including being creditworthy with a reasonable ability to repay and being unable to get the desired credit on reasonable terms from non-government sources. The page does not say a prior denial, or a rejection letter, is required or is enough to meet any of them. Your lender decides fit.
A short readiness check before you resubmit anywhere:
- You know the stated reasons, or asked for them and noted the date.
- Each reason is sorted as a file, fit or repayment issue.
- Every file issue has a fix, and your documents agree with the application.
- The amount, use of funds and product match what the lender or program describes.
Sources
- Consumer Financial Protection Bureau, “§ 1002.9 Notifications,” Regulation B, including official interpretation (undated; retrieved October 22, 2026): https://www.consumerfinance.gov/rules-policy/regulations/1002/9/
- U.S. Small Business Administration, “7(a) loans” (undated; retrieved October 22, 2026): https://www.sba.gov/loans/7a-loans/
- U.S. Small Business Administration, “Microloans” (undated; retrieved October 22, 2026): https://www.sba.gov/loans/microloans/
About the author
The Credisian Editorial Team writes plain-English guides and news on business credit and borrowing, sourced and checked under our editorial policy, to help owners make informed funding decisions.